 VN
 EN
For many years, hotel distribution strategies have largely focused on major players such as OTAs, direct websites, and large-scale tour operators. This is understandable, as a Phocuswright report (2025) indicates that over 70% of global online booking revenue is currently concentrated on a few key platforms, with OTAs holding a dominant share. However, this excessive focus on "top-tier" channels has inadvertently created a significant gap in the distribution ecosystem, where secondary channels and new platforms remain underexploited.
As travel consumer behaviour becomes increasingly fragmented, customers no longer follow a linear journey. They might search on Google, check reviews on social media, purchase vouchers through affiliates, or book services via super apps. According to Google Travel Insights (2025), the average customer booking journey now involves 5–7 different touchpoints before a final decision is made. This means that if a hotel only has a strong presence on a few main channels while neglecting these "satellite touchpoints," it is limiting its ability to reach customers. This is precisely why the article “DECODING HOTEL PLACE STRATEGY – PART 5: Lack of Diversification in Ancillary Channels and New Platforms” focuses on analysing a less-discussed issue with long-term impact: how a lack of flexibility in expanding distribution channels can cause hotels to lose their competitive edge in a rapidly changing market.
Current Situation: When the distribution ecosystem is "off-balance"
In the distribution landscape of most 4–5 star hotels in Vietnam today, a familiar yet risky structure is easily observed: an over-reliance on a few key channels. International OTAs, direct websites, and a few major travel partners often account for 80–90% of total room revenue, creating an ecosystem that appears "efficient" but actually lacks depth and flexibility. According to Savills Hotels (2025), in many urban hotels and luxury resorts, OTAs alone contribute 50% to 70% of total bookings during the low season – a period when the pressure to fill rooms is highest. Conversely, ancillary channels such as small agencies, collaborators, or new platforms account for less than 10%, and in many hotels, are barely recognised as a significant revenue source.
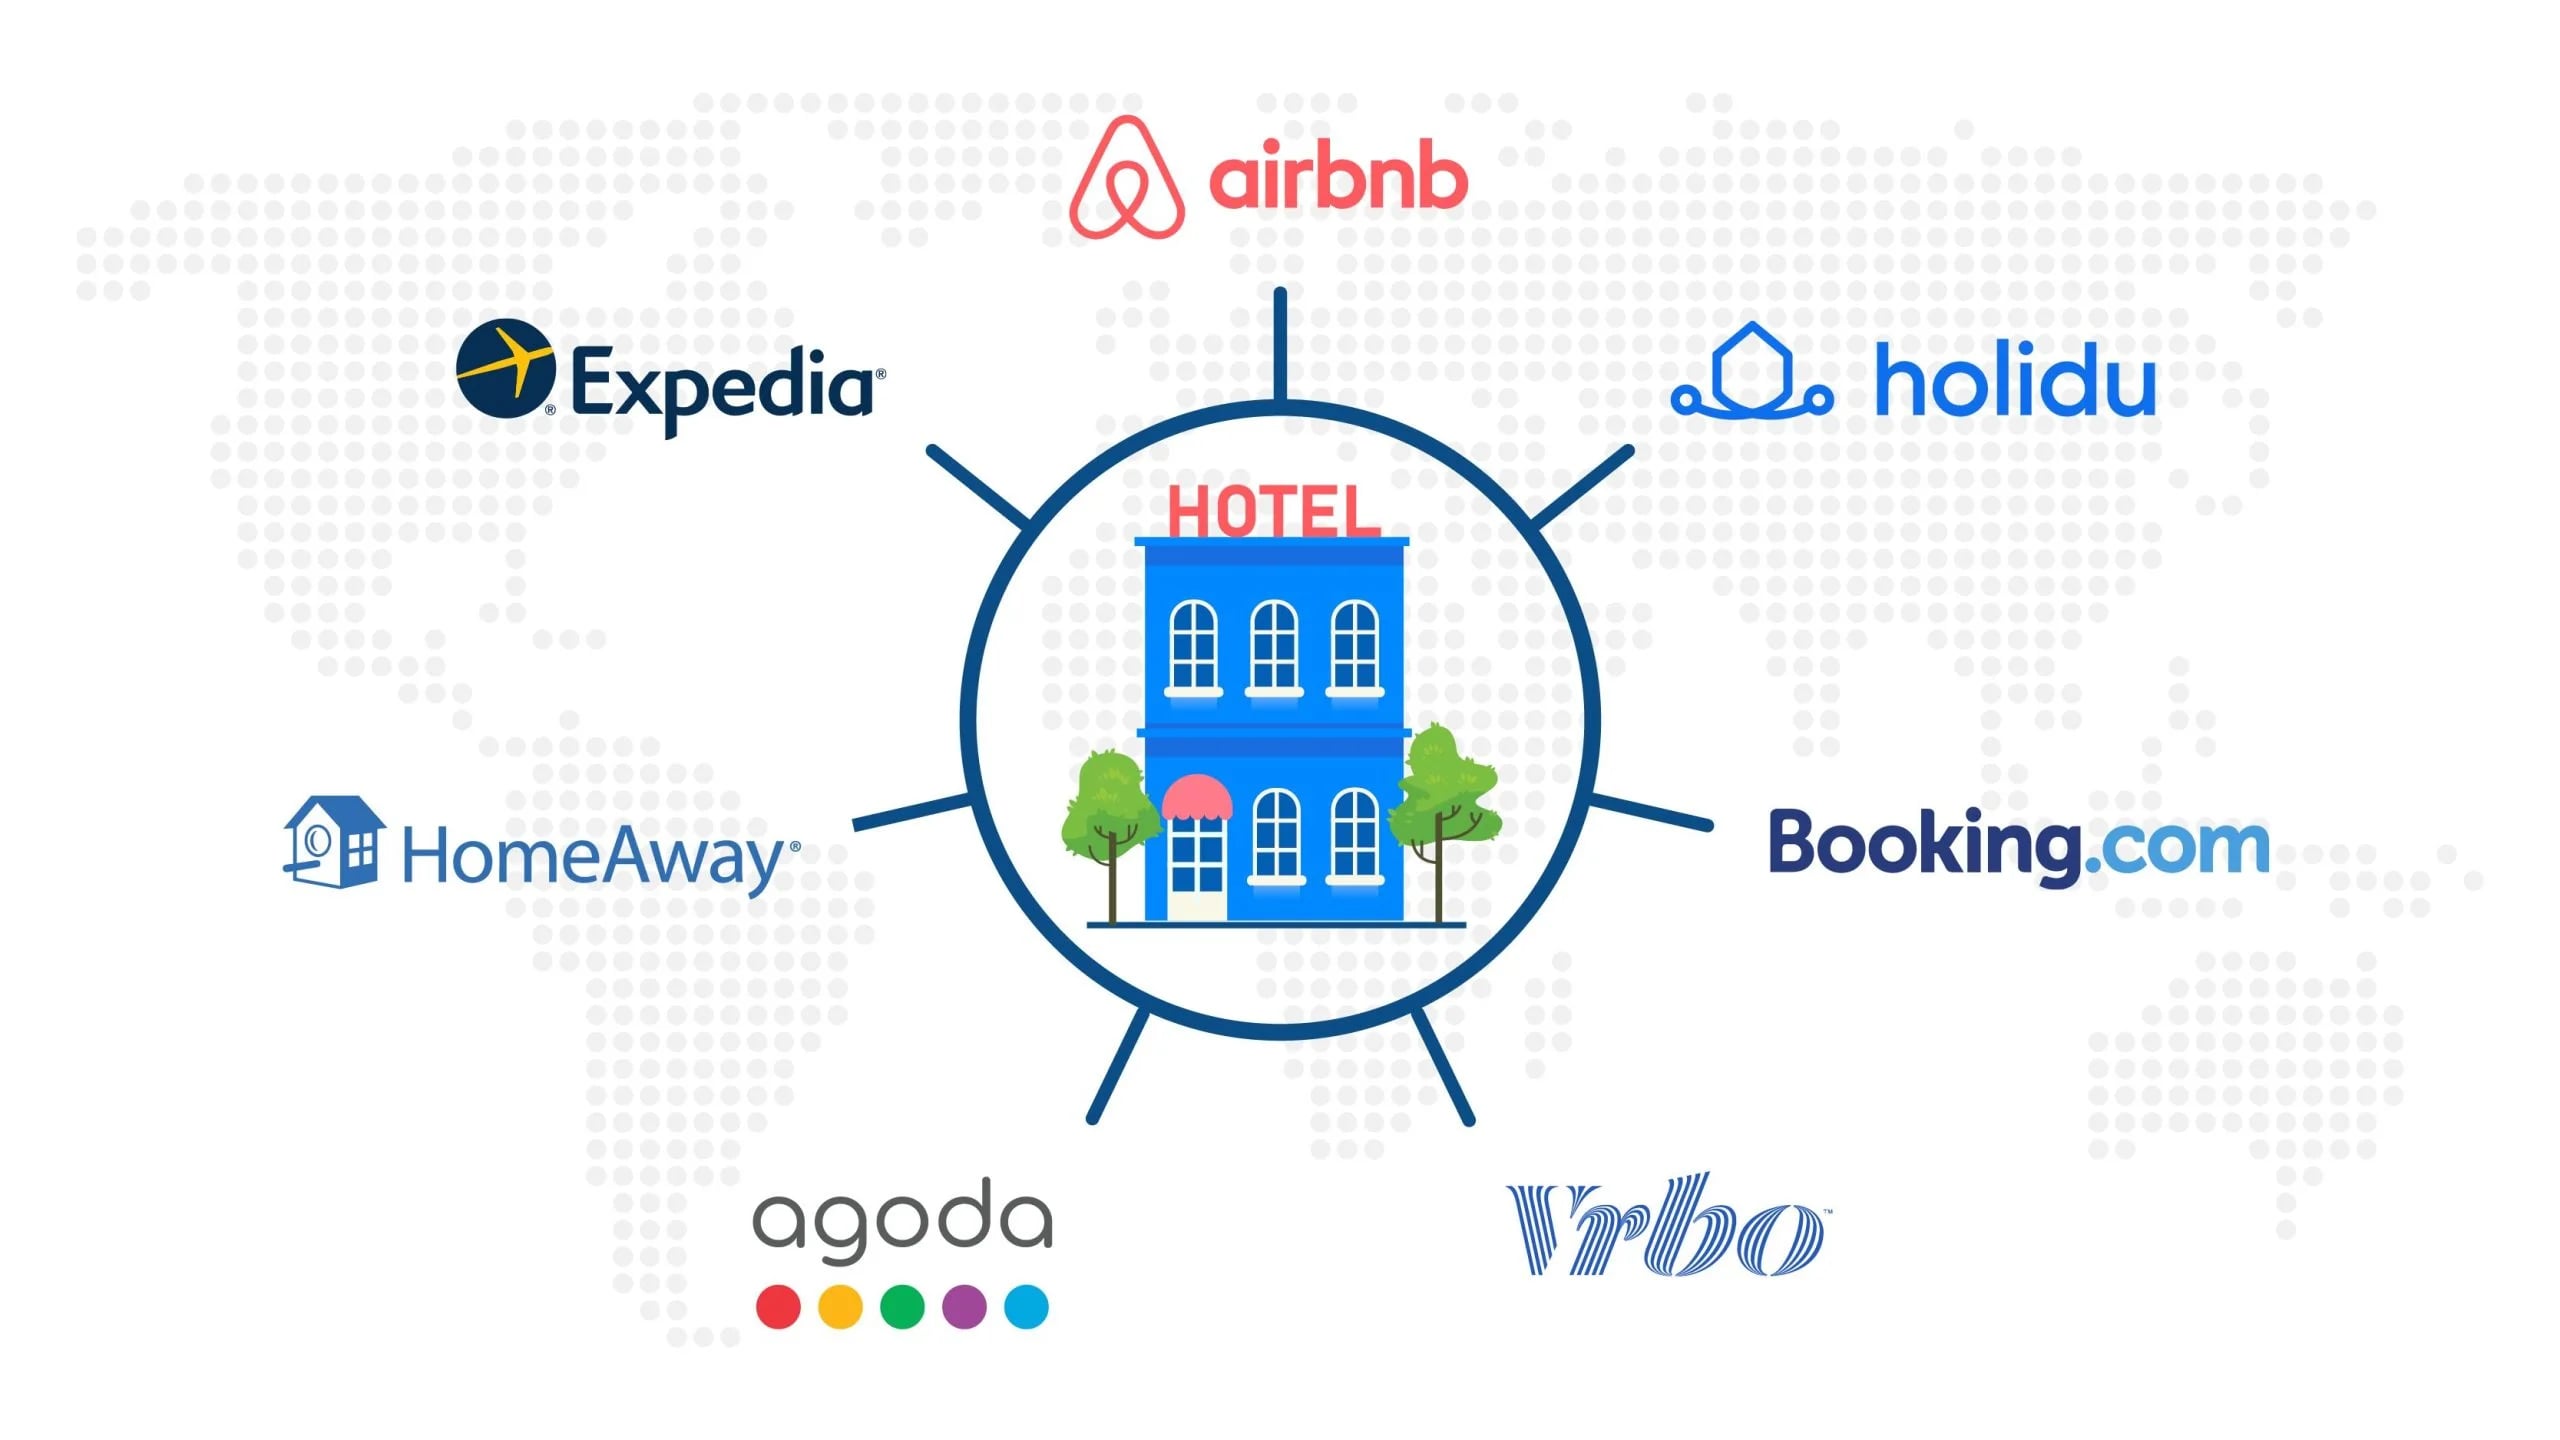
This "off-balance" situation is not just about revenue share; it also reflects how hotels perceive and operate their distribution ecosystem. Channels like local agencies, social media room sellers, online voucher platforms, or travel integration apps within banking/e-wallet ecosystems still exist, but have not been incorporated into a systematic exploitation strategy. Meanwhile, consumer behaviour is shifting rapidly. According to Statista (2025), over 60% of users in Southeast Asia are willing to book travel services directly on the "super apps" they use daily, from banking apps and e-wallets to e-commerce platforms with integrated travel services. This means that if hotels are not present on these platforms, they are missing out on a large "flow of demand" right from the first touchpoint.
Concurrently, the rise of regional and specialised platforms is reshaping the distribution game. Platforms like Klook, Traveloka, and Trip.com are not merely room booking channels; they also integrate travel experiences, attraction tickets, packages, and ancillary services – thereby strongly attracting young travellers and independent tourists. According to Skift (2025), Trip.com recorded double-digit growth in the Southeast Asian market, especially among Asian travellers who tend to book services as part of an all-inclusive ecosystem. However, the reality shows that many hotels in Vietnam still approach these platforms cautiously – participating only on an experimental basis, without a clear strategy to optimise revenue and data from these channels. The result is an increasingly clear paradox: while hotels are "crowding" to compete on primary channels with ever-increasing distribution costs, from OTA commissions to digital marketing expenses, the "blue oceans" in ancillary channels and new platforms remain underexplored. This is not only a waste of growth opportunities but also makes the distribution ecosystem imbalanced, lacking scalability, and vulnerable to market fluctuations.
Cause: When resources and mindset fail to keep pace with the market
One of the core reasons for the "lack of channel diversification" is not that hotels lack options, but rather how resources are allocated – in terms of people, budget, and operational mindset. In a context where revenue and sales & marketing teams in many hotels are still lean, short-term revenue pressure often leads to prioritising channels capable of "generating immediate bookings" such as OTAs or direct websites. According to Hotel Tech Report (2025), over 60% of hotels in Asia admit they lack sufficient resources to effectively manage and optimise more than 5–7 distribution channels simultaneously. This leads to a familiar reality: operational teams spend most of their time optimising OTA rankings, managing rates and promotions, while ancillary channels are largely "neglected" or maintained at a minimal level. A typical example can be seen in many boutique hotels or medium-sized resorts in destinations like Ha Long or Phu Quoc. The revenue department daily monitors the prices of dozens of competitors on OTAs, constantly adjusting rates to maintain display rankings, while coordinating with marketing to run Google or metasearch ads. In this cycle, establishing relationships with a network of room-selling collaborators, or experimenting with a new platform like a travel-integrated banking app, is almost never on the priority list – not because it's ineffective, but because there's "no time to do it."
Beyond resource constraints, risk factors also make many hotels hesitant to engage with smaller channels. Local agents or collaborators often operate in a fragmented manner, lack transparent evaluation systems, have unstandardised payment processes, and pose potential credit risks. In contrast, working with large OTAs, despite high commission costs, ensures cash flow, clear processes, and control. For example, a hotel might accept paying 18–22% commission to an OTA for confirmed bookings and near-instant payment, rather than partnering with a small agent who might deliver a similar volume of guests but with 30–45 day payment delays. This "operational safety" leads many hotels to choose familiar paths, even knowing that distribution costs will increase in the long term. Another significant barrier stems from technology and system integration capabilities. Expanding to many new channels is not merely about "listing more"; it requires a robust operational platform to synchronise prices, room inventory, and customer data in real-time. According to Oracle Hospitality (2024), only about 45% of hotels in the Asia-Pacific region have implemented channel manager and CRS systems flexible enough for multi-platform integration. In reality, many hotels still handle secondary channels manually – receiving bookings via email, updating Excel, then re-entering data into the system, leading to a high risk of errors. For instance, a collaborator selling rooms via Facebook might successfully close a deal, but if the information isn't updated promptly in the PMS, overbooking can easily occur if an OTA sells at the same time.
Furthermore, the mindset factor, though less discussed, significantly influences how hotels approach ancillary channels. Some hotels, especially in the 4–5 star segment, maintain a "channel selection" approach to protect their brand image, thereby limiting cooperation with online collaborators, voucher platforms, or "mass-market" sales channels. However, with rapidly changing consumer behaviour, the line between "premium" and "mainstream" in the booking journey is increasingly blurred. A customer might be willing to spend tens of millions of VND on a 5-star resort stay but will seek deals through a Facebook group or purchase vouchers via an intermediary platform to optimise costs. If hotels are not present at these touchpoints, they not only miss a transaction but also miss the opportunity to reach a high-value customer segment with highly "omnichannel" consumption behaviour. Overall, it can be seen that the lack of distribution channel diversification does not stem from a single cause, but is the result of a combination of resource limitations, risk aversion, technological barriers, and even preconceived notions in operational thinking. And it is the synergy of these factors that has led many hotels, despite recognising the potential of ancillary channels, to not yet truly act to effectively exploit them.
Consequence: Missing ancillary channels means missing growth opportunities
The lack of distribution channel diversification, on the surface, might simply be understood as "missing out on a few small revenue streams." However, in the context of an increasingly fragmented and consumer behaviour-driven tourism and hospitality market, this is a strategic issue directly impacting a hotel's long-term competitiveness. Firstly, the most obvious consequence is that hotels lose opportunities to reach new customer segments – groups that are increasingly accounting for a large proportion of total market demand. Modern travel consumption behaviour is no longer confined to a few familiar platforms but spans various "touchpoints": from social media, review platforms, and mobile applications to integrated service ecosystems. In particular, younger guests like Millennials and Gen Z – who are becoming the "growth engine" of the tourism industry – tend to search for and book services in a completely different way than previous generations. They might read reviews on TikTok, hunt for deals in Facebook communities, or book holiday packages through platforms like Traveloka or Klook. According to Deloitte (2025), over 55% of travellers in these two groups in Asia prioritise using integrated apps or mobile platforms during the booking process. This means that if hotels are not present on these channels, they are almost "out of the game" from the moment customers begin their search.
Beyond losing customers, a lack of diversification also leads hotels to become increasingly dependent on primary channels. When most revenue is concentrated on a few platforms like OTAs or major partners, any change from these channels – from display algorithms and commission policies to marketing strategies – can have an immediate impact on revenue. This is a form of "systemic risk" in distribution: without supplementary channels, hotels lack sufficient "buffers" to absorb fluctuations. For example, if an OTA changes its ranking system or increases display costs, a hotel could immediately lose a significant volume of bookings without alternative channels to compensate. In contrast, entities with diverse channel ecosystems are often more flexible in reallocating customer sources, thereby mitigating negative impacts. Another significant, but often underestimated, consequence is that hotels are slow to adapt to new technological trends and consumer behaviour. New platforms are not merely "additional sales channels" but also play a role in shaping how customers search, compare, and make decisions in the future. Not participating early causes hotels to miss out on the "first mover" advantage – a crucial factor in the digital environment where pioneering platforms often gain user loyalty. Meanwhile, more agile competitors, willing to experiment and optimise on new platforms, can quickly build their position and capture market share in emerging customer segments.
In the long term, all these factors converge into a structural problem: the hotel's distribution ecosystem becomes "narrowed," lacking depth and difficult to expand. While the market is increasingly diverse, customer behaviour is increasingly fragmented, and technology constantly creates new touchpoints, an inflexible distribution system will be unable to keep up. This not only reduces business efficiency in the short term but also weakens long-term competitiveness as the hotel no longer controls its customer flow, but must rely on external channels to sustain growth.
Solution: Building a multi-layered and flexible distribution ecosystem
To address this challenge, hotels need to shift from a "channel-centric" mindset to a "multi-layered channel" approach, where every channel, big or small, plays a specific role in the customer journey. First, a clear channel classification strategy is needed, distinguishing between primary and supplementary channels. Secondary channels do not necessarily need to generate large immediate revenue, but they play a role in expanding market reach and accessing niche segments. Designing flexible partnership policies, such as using dedicated booking codes and performance-based commission structures, will help hotels leverage collaborators and small agents without investing excessive resources.
Alongside this, technology is an indispensable factor. Implementing a modern channel manager system, integrating APIs with new platforms, and synchronising data helps hotels manage multiple channels without significantly increasing operational costs. NewSun Hospitality currently assists hotels in selecting and implementing suitable technology systems, ensuring long-term channel scalability. From a market perspective, hotels need to proactively engage with new platforms rather than waiting. Early experimentation with platforms such as metasearch, super apps, or regional OTAs will help hotels better understand customer behaviour and optimise their distribution strategy.
Throughout this journey, the role of a strategic consulting firm like NewSun Hospitality extends beyond merely "adding channels"; it involves designing a structured and scalable distribution ecosystem. From assessing current channel status, developing a comprehensive Place strategy, selecting and implementing technology, to training operational teams – NewSun aims to help hotels not only diversify channels but also optimise efficiency across each channel. This is because, in an increasingly competitive market, the advantage lies not in "being everywhere," but in the ability to appear at the right time, on the right channel, and meet the customer's exact needs.
Conclusion: Diversification – the key to sustainability
In a market where customer behaviour constantly changes and technology continuously evolves, relying on a few fixed distribution channels is no longer a safe strategy. Conversely, the ability to adapt, expand, and restructure the channel ecosystem is crucial for sustainability. "Lack of channel diversification" is not an easily noticeable problem, yet it is one of the silent causes undermining the competitiveness of many hotels. If revenue is the outcome of strategy, then the distribution ecosystem is its foundation. NewSun Hospitality is ready to partner with hotels in building a flexible, multi-layered, and optimised Place ecosystem – where each channel is leveraged effectively to drive sustainable growth.
- Hotline: +84 768 68 2913
- Email: dosm@nshm.com.vn
- Zalo OA: https://zalo.me/2452770272256938463 (NewSun Hospitality)
- Website: https://nshm.com.vn/ (NewSun Hospitality)
References
- Phocuswright (2025). Global Online Travel Market Report
- Google (2025). Travel Insights & Consumer Journey Data
- Savills Hotels (2025). Vietnam Hotel Market Overview
- Statista (2025). Southeast Asia Travel & Super App Usage
- Skift Research (2025). Asia-Pacific Travel Distribution Trends
- Hotel Tech Report (2025). Hotel Distribution Technology Survey
- Oracle Hospitality (2024). Hotel Technology Adoption in APAC
- Deloitte (2025). Travel & Hospitality Industry Outlook